How Much Does It Cost to Finance Solar Panels? A Real Cost Breakdown
Most homeowners don’t write a check for a solar array. They borrow the money, and the question that follows is almost always the same: how much does it cost to finance solar panels? The short answer is that a typical financed system adds roughly 20% to 60% to the upfront price once interest is factored in, and your monthly payment usually lands somewhere between $120 and $320 depending on the size of the system, the loan term, and your credit.
Those numbers move around a lot, which is exactly why so many quotes are hard to compare. One installer will pitch a “0% APR” loan that quietly tacks a dealer fee onto the principal. Another will offer a clean market-rate loan with no fees but a higher monthly stuck on top. Understanding the mechanics — not just the rate — is the only way to know what you’re actually paying.
Below, I break down real financing costs line by line, compare the most common options side by side, and show you how to cut the total price before you sign anything.
How Solar Financing Actually Works
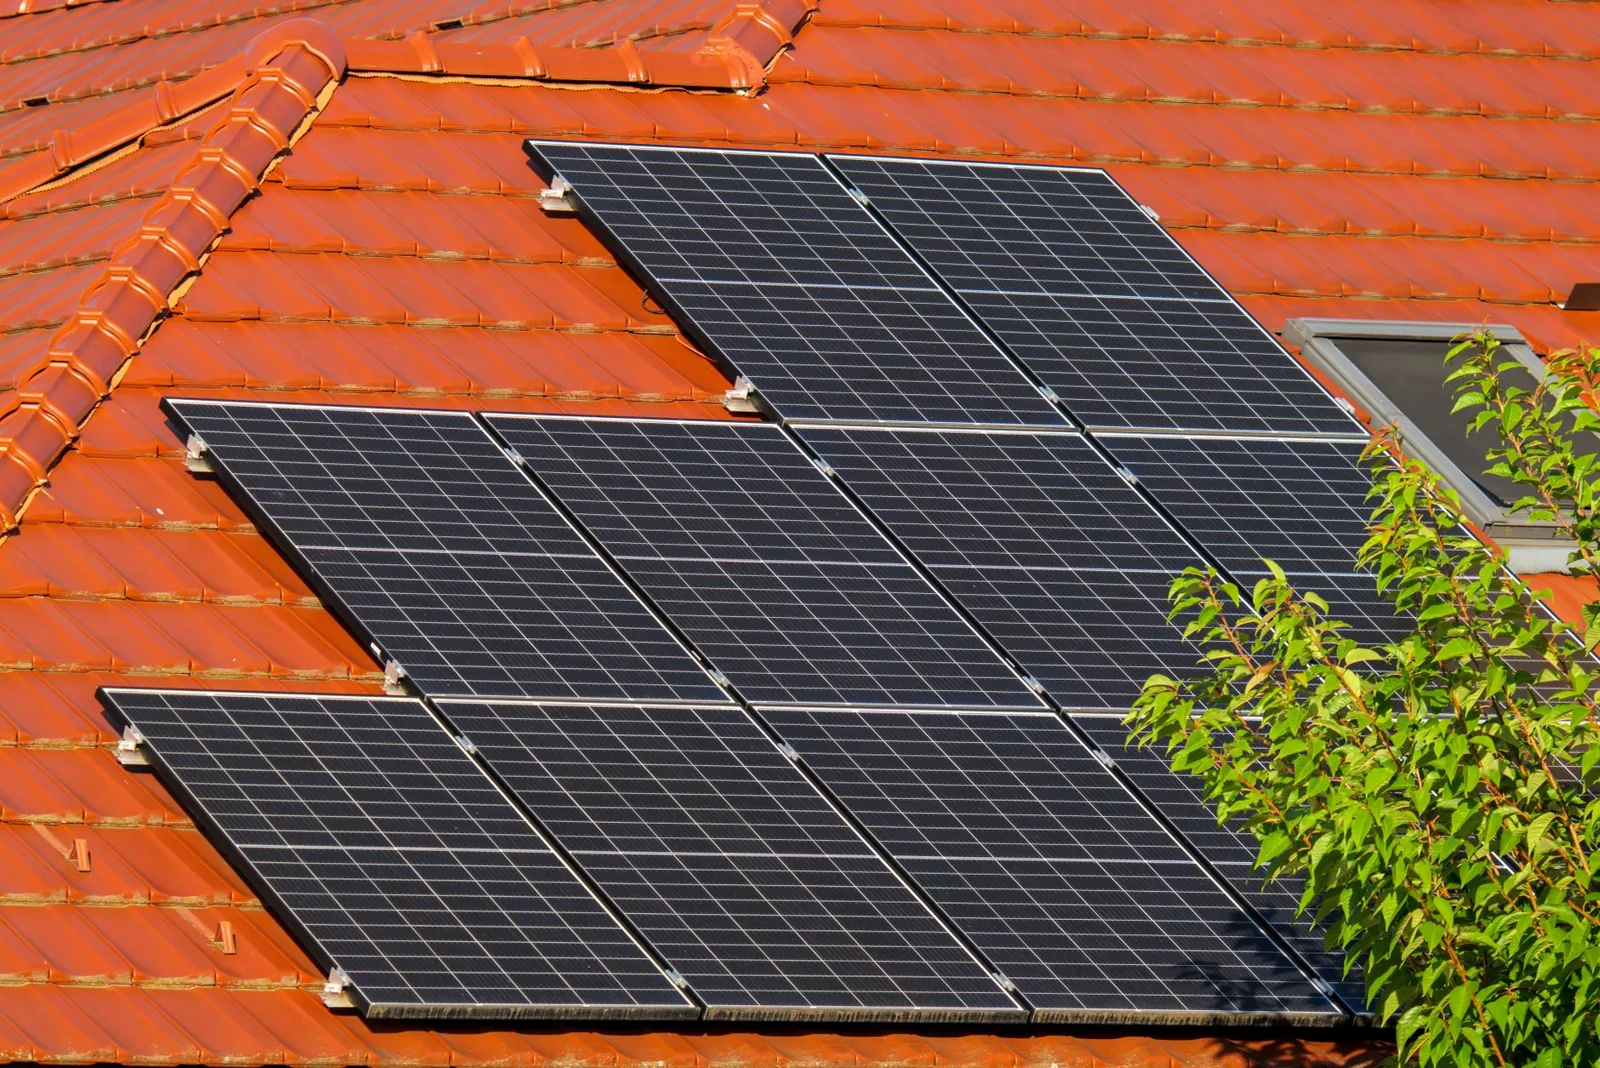
When you finance solar panels, you’re not paying for electricity directly. You’re paying back a loan, and the size of that loan is set by the cash price of the system. On most US homes, that’s a 7 to 11 kilowatt (kW) array priced at roughly $2.50 to $3.50 per watt installed.
That means a typical 7kW system costs around $17,500 to $24,500 before incentives, and a 10kW system runs $25,000 to $35,000. Whatever you borrow, you then repay with interest over 5 to 25 years. Your financing cost is simply the difference between what you borrow and what you pay back in total.
Two forces shape that number more than anything else: the interest rate, and the loan term. A low rate on a long term can cost you more in total than a higher rate on a short term, because interest has more time to accumulate.
How Much Does It Cost to Finance Solar Panels?
Let’s put real numbers on it. Take a $20,000 solar loan — a common figure after a down payment on a mid-size system — and see what it costs across different terms at a 7% APR, a typical rate for a borrower with good credit.
- 10-year term: about $232 per month, $27,840 total, roughly $7,840 in interest.
- 15-year term: about $180 per month, $32,400 total, roughly $12,400 in interest.
- 20-year term: about $155 per month, $37,200 total, roughly $17,200 in interest.
- 25-year term: about $141 per month, $42,360 total, roughly $22,360 in interest.
The pattern is the important part. Stretching the term drops your monthly payment by about $90, but it more than doubles your total interest. A 25-year loan on the same $20,000 system costs over $22,000 just to borrow the money — more than the system itself.
Now shift the rate instead. At 9% APR over 20 years, the same $20,000 loan runs about $180 per month and $43,200 total. At 5%, it’s about $132 per month and $31,680 total. A four-point swing in APR changes your lifetime cost by more than $11,500. This is why shopping the rate, not just the monthly payment, is where the real savings live.
Financing Options Compared, Side by Side
You can pay for solar through several channels, and they produce very different cost structures. Here’s how the four most common stack up on a $22,000 system.
| Factor | Solar Loan | HELOC | Cash-Out Refinance | PPA / Lease |
| — | — | — | — |
| Typical APR | 4%–11% (plus possible dealer fee) | Variable, 7%–9% | Current mortgage rate | No APR; fixed payment |
| Upfront cost | $0–$3,000 down | Closing costs, often $0 | 2%–5% of loan in fees | $0 |
| Monthly payment | $130–$250 | Interest-only early, then higher | $140–$250 (folded into mortgage) | $90–$180 (rises yearly) |
| You own the system | Yes | Yes | Yes | No |
| Federal tax credit | You claim it | You claim it | You claim it | Installer keeps it |
| Best for | Buyers with good credit | Homeowners with strong equity | Homeowners refinancing anyway | No-money-down buyers |
A solar loan is usually the cleanest path if your credit is solid and you want the 30% federal tax credit. A home equity line of credit (HELOC) can beat a solar loan’s APR, but the rate is variable, so your payment can climb. A cash-out refinance makes sense only if you were already refinancing at a better mortgage rate. A power purchase agreement (PPA) or lease looks cheap because it’s $0 down, but you never own the panels and the payment typically escalates 2% to 3% every year.
What You’ll Pay Over the Life of the Loan
Monthly payments tell you whether the loan fits your budget today. Total payments tell you whether it makes sense at all.
On a $24,000 system financed for 20 years at 7%, you’ll pay around $186 a month and just under $44,600 over the life of the loan. That’s roughly $20,600 in interest on top of the principal. Knock the term down to 10 years and the same system costs about $279 a month, but only $33,480 total — saving you more than $11,000 in interest.
Then there’s the dealer fee, the quiet cost on “low APR” solar loans. Many installers advertise rates of 0.99% to 3.99% by paying a dealer fee upfront, often 15% to 30% of the loan amount. That fee is baked into your principal. A $24,000 system with a 22% dealer fee becomes a nearly $30,800 loan before a single payment is made. The rate looks great, but you’re financing a bigger balance — and paying interest on a fee you never saw itemized.
The right comparison is always total cost of borrowing: principal plus all fees plus all interest. If an installer won’t show you that number in writing, treat that as a red flag.
Factors That Drive Financing Costs Up or Down
Your quoted financing cost isn’t random. Five factors do most of the work.
- Credit score. Borrowers over 740 regularly qualify for solar APRs in the 4% to 6% range. Below 640, expect 9% to 11% or outright denial.
- System size. Bigger systems mean bigger loans and bigger interest, even at the same rate. Sizing the system to your actual usage keeps this honest.
- Loan term. As shown above, longer terms raise total interest dramatically in exchange for a lower monthly.
- Dealer fees. Low-rate loans usually carry hidden dealer fees that inflate the principal by thousands.
- Down payment. Every dollar you put down is a dollar you don’t finance and don’t pay interest on.
Your choice of installer matters too. National names like SunPower (now going through restructuring) and Sunrun tend to price higher than quality regional installers, and that higher cash price becomes a higher loan. See our breakdown of what a solar panel actually costs to install before you accept any financing quote.
How to Cut Your Solar Financing Costs
The single biggest lever is the federal Investment Tax Credit. Through 2032, the credit covers 30% of your system’s installed cost, and it applies whether you pay cash or take a loan. On that $24,000 system, that’s $7,200 back at tax time — enough to knock a meaningful chunk off your monthly payment if you apply it to the balance.
State and utility rebates stack on top. New York, Illinois, California, and many other markets run their own incentive programs, and the combination can push your effective price down by 40% or more. If you’re weighing options, the guide on how much the solar rebate is worth walks through the current numbers.
Beyond incentives, three habits lower financing cost almost every time:
- Shop at least three lenders. Getting quotes from a solar lender, a local credit union, and a HELOC lets you push each rate down against the others.
- Ask for the no-dealer-fee option. A 6.99% loan with no fee usually beats a 3.49% loan with a 25% fee when you do the math.
- Keep the term short. Choose the shortest term whose payment you can comfortably cover, and prepay without penalty whenever possible.
For current benchmarks and deeper how-to detail, the team at Energy.gov keeps regularly updated reference guides worth bookmarking.
Frequently Asked Questions
Are solar loan payments usually lower than your electric bill?
Often, yes. Most homeowners land a solar payment between $120 and $250 a month, while the average US electric bill sits in the $125 to $170 range. The gap closes once the loan is paid off, when production is effectively free for years.
Can I get solar panels with no money down?
Yes. No-money-down solar loans and leases are widely available, but they aren’t free. The cost is pushed into a higher principal or a long, escalating payment, so read total cost carefully.
Is a solar loan tax-deductible?
Not in the way a mortgage is. Interest on a solar loan isn’t deductible unless the loan is a home equity product and the funds went to home improvement — and even then it depends on your tax situation. What you can claim is the 30% federal tax credit on the system itself.
Does financing solar hurt my credit score?
The application triggers a hard inquiry, which can shave a few points temporarily. On-time payments typically help your score over time, while a missed payment will drop it like any other installment loan.
How do solar loans compare to HELOCs in 2024 and 2025?
HELOCs have run slightly below dedicated solar loans on rate for prime borrowers, but their variable rates can rise. Solar loans carry fixed rates, which makes budgeting easier, even when the APR is a point or two higher.
The Bottom Line
How much does it cost to finance solar panels? For most homes, between roughly $3,500 and $22,000 in total interest depending on the loan size, rate, and term — on top of the system’s cash price. A $20,000 loan at 7% costs about $7,840 in interest over 10 years and more than $22,000 over 25.
Before you sign, get the itemized total cost of borrowing in writing, confirm whether a dealer fee is hidden in the principal, and check your rate against at least one competing lender. If you’re comparing your options, the run-down on how much a solar panel loan costs lays out the numbers in more detail. And to see how financing compares with paying cash once, start with the straight cost of a typical solar panel. The cheapest loan is the one you fully understand — so run the real math before the pitch runs it for you.